Each year, private equity investors in the U.S. middle market are responsible for deploying hundreds of billions of dollars across thousands of discrete transactions.
These deals don’t often make headlines. In many ways, however, they’re the engine of the PE industry, a space that has experienced remarkable growth over the past two decades.
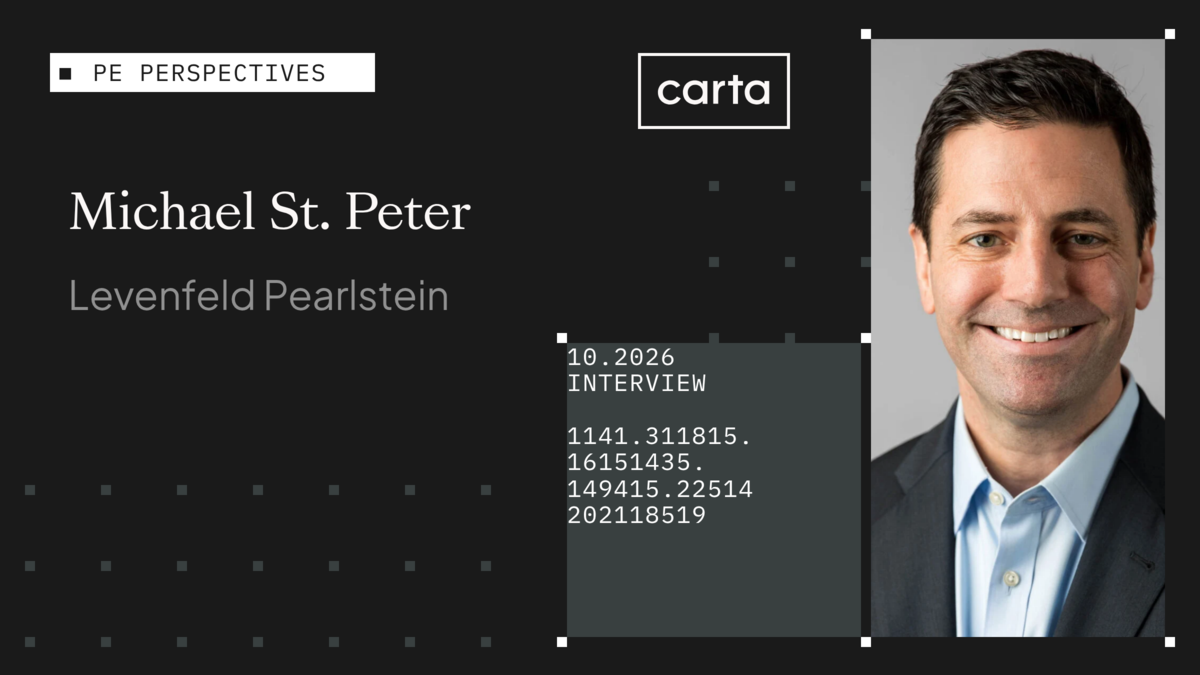
In his practice as a partner at Levenfeld Pearlstein, Michael St. Peter has had a front-row seat to PE’s ongoing expansion. St. Peter has 20 years of experience working closely with middle-market private equity firms and their portfolio companies in a number of areas, including new capital raises, restructurings, and organizing and executing complex buyouts.
In 2026, he’s seen the middle market start to shift in a number of ways that could have serious implications for dealmakers and executives alike.
In this conversation, which has been edited for length and clarity, St. Peter shares his firsthand perspective on how the overall PE market is evolving, why middle-market firms are growing more selective in their investments, which sectors are generating the most interest, and why investors are pursuing new strategies to achieve the valuation growth they need across their portfolios.
CARTA: Overall, what has activity in the middle market looked like so far this year?
MICHAEL ST. PETER: In 2026, selectivity is defining the market. The strong companies continue to attract significant interest from PE investors, but buyers are being more disciplined and focused on the quality of the business. That includes things like the recurring revenue of the business, the margins, and the general investment execution probabilities.
How does what we’re seeing in the middle market today compare to what’s taking place in the upper and lower ends of the PE market?
Across the whole PE market, there is an element of bifurcation going on. Clearly, the high-quality companies with the characteristics we discussed are generating very competitive processes. Capital is concentrating among the highest-quality platforms. Less differentiated businesses without the margin sustainability, with lower multiples, they’re seeing less robust auction processes.
I think the middle market mirrors the larger-cap PE market in the growing bifurcation between the great companies and the less great companies. With the middle market, there’s still a lot of diamonds in the rough. There’s a lot more attention being placed on companies that may not fit a profile for a large transaction, but could be acquired at a lower purchase price and brought into an existing platform to gain some value accretion. That leads to a lot of the add-on activity we’re seeing.
You mention how competitive bidding processes have been. That aligns with recent data on how the size of the average PE deal has been increasing. What does that mean for middle-market funds and their strategies around fund deployment, when prices and multiples are maybe higher today than investors expected when they raised these funds?
They probably are doing fewer deals focused on larger platforms. If you’re doing larger deals, and perhaps at larger valuations, the kind of multiple expansion that historically PE has relied upon is not going to be as easily achievable. So with a larger platform, that’s going to drive more interest in add-ons or using a roll-up strategy to acquire smaller companies that can create value. For example, if a fund has $100 million of equity to deploy, they’re maybe less likely today to do five deals at $20 million apiece, and more likely to do two deals at $40 million apiece and reserve the rest of their equity for add-ons under those platforms. That’s one change that bifurcation is forcing middle-market sponsors to consider.
As you say, the steady expansion of multiples used to be a major part of the playbook for how PE portfolio companies would accrue value over time. It sounds like that isn’t the case in the same way it used to be?
Ten years ago, that kind of multiple expansion from the time a PE firm invests in a company to the time it exits the company was just part of the playbook. Obviously, you had to create value during that period to justify the increased multiple, but that was a natural part of the investment thesis. While multiple expansion still occurs, particularly when a company achieves greater scale or enters a different buyer universe, today’s returns are increasingly driven by operational improvement and strategic execution.
With middle-market funds turning to more add-ons in this environment, is the theory that building those types of platforms is a way to access the sort of multiple expansion that is growing harder to achieve as a standalone company?
That’s part of it. If you take a company that has $5 million in EBITDA and grow it to $20 million, you enter a whole new pool of potential buyers. So there is a strategy to grow EBITDA to enter into potential new markets for an exit. But that doesn’t happen just by growing EBITDA. With add-ons, you have to add value operationally, through more efficient operations, professionalized management, all those things.
The other thing is, most middle-market industries remain highly fragmented, much more than the large-cap industries. A lot more companies out there, and a lot more smaller companies. Add-ons allow sponsors to really accelerate growth, build scale, and expand capabilities faster than they could organically. They’re also a way to expand geographically—let’s say you have a platform that serves the southeast, and you can do add-ons in neighboring states to grow your reach.
When prices get higher and competition for the assets at the top of the PE market increases, what sort of trickle-down effect does that have on the middle market?
I do think you’re seeing more funds kind of reach down into the middle market. The mega-cap deals remain highly competitive and difficult to source. So you’re seeing funds that maybe did not have a company below $100 million of enterprise value in their portfolio that now are reaching down below that threshold to try to find those diamonds in the rough, and then use strategies to grow them. There continues to be significant competition among sponsors for high-quality assets.
So, to wrap up a couple different threads here: It sounds like, in your view, the reason fewer deals are taking place across PE today is much more about investors being more selective amid an environment where they have to pay higher prices than they used to, rather than any sort of shift in the underlying quality of companies in the market?
I definitely think that’s true.
Are there any industries where you’re seeing particular interest among middle-market investors?
We’re seeing continued strong activity in business services and healthcare services. Healthcare has been strong for several years now. I would also mention specialized industrial and manufacturing businesses—those high-margin, specialized businesses continue to be attractive for private equity. Investors are really gravitating toward companies with resilient earnings and clear growth opportunities, and those sectors fit that profile. And then you have to mention the AI and technology-enabled services, machine learning, all of those specialties that can apply across industries.
I imagine that investing in AI can mean something different for middle-market PE firms than for other types of investors. What does AI look like today in this area of the market?
It’s really about the business services segment, and how those business service providers are utilizing either proprietary AI or third-party AI in new ways or in efficient ways to service their own customer base and grow sales. It’s also in healthcare, where there’s a clear thesis around how AI will make healthcare more efficient. I think it’s particularly in business services and healthcare services where that utilization of AI is most heavily reviewed.
An overarching trend across financial markets in recent years has been higher interest rates becoming the norm. What sort of impact has this had on the middle market, particularly in terms of finding financing for deals?
Yes, rates are higher than they used to be. But the debt financing is still available. There are a lot of private credit funds and traditional middle-market debt lenders and mezzanine lenders that remain active in pursuing loans. But higher interest rates require more discipline. You probably need larger equity checks at the start, because you’re getting less leverage to start, and higher interest rates will create higher debt service on the companies. That’s driving some of the discipline. When a sponsor knows they have to service a certain amount of debt at a certain interest rate for the life of an investment, they’re going to be more selective.
The private credit industry has, of course, fallen under some significant scrutiny this year related to redemption requests and the sector’s overall opacity. Have any of those shockwaves reached the middle market?
I have not seen it impact the middle market. As I said, there’s still a lot of available financing out there. That’s not to say it’s the same as it was in 2018 or 2019, or in 2006 or 2007. But it’s available. There are so many types of lenders that I think these quality assets are very financeable.
After the market reset in 2022, we saw bid-ask spreads widen considerably in the private markets, with the result of fewer transactions taking place. In terms of the prices companies are asking for and what buyers are willing to pay, what does the middle market look like today?
I think it’s normalized a bit compared to three or four years ago, when there was some real pie-in-the-sky thinking on the part of sellers. Part of that is natural market cycles. Part of it is, in the middle market and the lower middle market, sellers and their advisors are more familiar with different structures to get a deal done. They’re more familiar with rollover equity into the platform company of the PE firm. They’re more familiar and comfortable with seller financing. They’re more familiar and comfortable with earnouts, which have become more common in recent years to bridge valuation gaps.
What sorts of metrics or thresholds are those earnouts most typically tied to?
It’s mostly based on EBITDA, on earnings. Sometimes a revenue-based earnout is simpler, and so sometimes that is preferred by sellers. Of course, PE firms get their returns based on increasing earnings and EBITDA, so paying an earnout only on revenue is riskier for them on the buy side. Sometimes, an earnout is even limited to a single customer or a single product line, where there’s some concern on the part of the buyer that a particular product line or customer will be as robust as is represented by the seller. Again, it shows that, overall, the parties and their advisors are becoming more comfortable with these kinds of highly structured deal elements, not just cash purchase price at close.
Subscribe to the Data Minute newsletter
DISCLOSURE: This communication is on behalf of eShares, Inc. dba Carta, Inc. ("Carta"). This communication is for informational purposes only, and contains general information only. Carta is not, by means of this communication, rendering accounting, business, financial, investment, legal, tax, or other professional advice or services. This publication is not a substitute for such professional advice or services nor should it be used as a basis for any decision or action that may affect your business or interests. Before making any decision or taking any action that may affect your business or interests, you should consult a qualified professional advisor. This communication is not intended as a recommendation, offer or solicitation for the purchase or sale of any security. Carta does not assume any liability for reliance on the information provided herein. This post contains links to articles or other information that may be contained on third-party websites. The inclusion of any hyperlink is not and does not imply any endorsement, approval, investigation, or verification by Carta, and Carta does not endorse or accept responsibility for the content, or the use, of such third-party websites. Carta assumes no liability for any inaccuracies, errors or omissions in or from any data or other information provided on such third-party websites. © 2026 eShares, Inc. dba Carta, Inc. All rights reserved. Reproduction prohibited.